

How to Identify and Reduce Risk in Your Contracting Business — Practical Strategies for Contractors

Risk in contracting is anything that threatens your ability to finish work, keep cash moving, meet regulations, or keep crews safe. This guide breaks those risks into clear buckets — financial, operational, legal/compliance, safety, and strategic — and gives hands-on steps you can start using today. You’ll learn how small issues become big losses, which controls stop that progression, and how sales and operational systems combine to strengthen outcomes. The payoff is concrete: fewer delays, healthier cash flow, fewer disputes, and smoother insurance conversations. Read on for problem-to-solution roadmaps and practical tactics you can apply to bids, schedules, crew checklists, and insurer discussions.
What Are the Key Types of Risks Facing Home Improvement Contractors?
Home improvement contractors commonly face five risk categories that shape business resilience: financial risks that squeeze margins and working capital; operational risks that cause schedule slips; legal and compliance risks that bring fines or litigation; safety risks that create injuries and claims; and strategic risks that threaten long-term continuity. Each category follows predictable patterns — late payments cause cash shortfalls, supply issues stall milestones, vague contracts invite disputes, on-site hazards trigger claims, and no succession or a narrow market makes shocks harder to survive. Spotting which risk dominates your operation points you to the right controls, letting you prioritize limited time and cash. The sections that follow unpack the financial and operational buckets with concrete threats and controls so you can assess immediate weak spots.
Here’s how the main risk types typically affect contractors.
| Risk Category | Primary Impact | Example & Likelihood |
|---|---|---|
| Financial Risk | Pressure on cash flow and shrinking margins | Late customer payments or underestimating jobs — high likelihood on small remodels |
| Operational Risk | Schedule delays and rising overhead | Material shortages or crew gaps — moderate to high likelihood in peak seasons |
| Legal/Compliance Risk | Fines, stop-work orders, or costly disputes | Expired licenses or vague contracts — moderate likelihood if controls slip |
| Safety Risk | Injuries, claims, and higher premiums | Missing PPE or training — variable likelihood but high cost when incidents occur |
| Strategic Risk | Threats to continuity and business value | No succession plan or too-narrow client mix — less frequent but high impact |
Use this comparison to decide which risks need immediate cash or operational controls and which can be scheduled for longer-term work.
Which Financial Risks Impact Contractor Profitability and Cash Flow?
Financial threats usually come from poor estimating, unmanaged change orders, late payments, weak job costing, and subcontractor failures — each one eats margin or ties up working capital. Underestimating a job forces last-minute margin recovery; untracked change orders convert work into unpaid labor and push up days sales outstanding. Small improvements to close rates or invoice timing can meaningfully reduce short-term borrowing and steady payroll. Practical defenses include disciplined job costing, enforceable payment terms (deposits and progress billings), retainers for long‑lead items, and basic client credit checks. These controls turn revenue surprises into predictable cash flow. The next section shows how money problems become operational headaches when schedules slip.
Financial Perspective on Contractor Risk Management
Construction firms face pressure from competition, new technology demands, and shifting customer expectations. Slow adoption of quality management and weak budget controls are notable risk factors. In emerging markets, political and legal uncertainties add systemic risk. Failures in safety controls and budgeting also increase financial exposure. Effective schedule and program management are critical to project success, and poor site conditions or safety practices further amplify project risk.
Quick financial fixes to prioritize:
- Require deposits: Collect funds up front to cover long‑lead purchases.
- Standardize change orders: Use written change orders tied to payment terms.
- Review job margins weekly: Compare costs to estimates and act on overruns fast.
How Do Operational and Project Risks Affect Construction Timelines?
Operational risks — supply hiccups, crew shortages, broken equipment, poor sequencing, and weather — ripple through projects as cascading delays, idle labor, and overtime that eat contingency. One late delivery can shift multiple trades and trigger rework. The best mitigations are redundancy and planning: build preferred-vendor lists, add buffer time for critical-path items, keep reorder points for common materials, and hold contingency funds sized to typical local delays. Track a few KPIs — lead time variance, on-time delivery rate, crew utilization — to see bottlenecks early and reassign resources before delays snowball. The next section gives a simple risk-impact matrix to match causes with the right controls.
Common operational causes and practical mitigations:
- Supply delays: Qualify backup suppliers and set reorder points for key parts.
- Labor shortages: Cross-train crews and keep a vetted subcontractor pool ready.
- Equipment failures: Schedule preventive maintenance and budget rental options.
How Can Contractors Effectively Mitigate Financial and Operational Risks?
Good mitigation mixes financial controls, the right insurance, and basic project discipline so losses are prevented or safely transferred. Financial steps — rigorous estimating, job-level accounting, upfront deposits, and clear payment milestones — make cash flow more predictable and reduce emergency borrowing. Proper insurance (general liability, workers’ comp, builders risk) shifts residual exposure to carriers. Project controls — baseline schedules, preferred-vendor agreements, and performance KPIs — expose delays early enough to correct them. Layer these tools to balance cost, complexity, and impact.
Use this quick comparison to match tools to the risks you face.
| Mitigation Tool | Cost / Complexity | Effectiveness & When to Use |
|---|---|---|
| Job Costing Software | Moderate / Moderate | High impact on margin control; use on recurring projects |
| General Liability Insurance | Varies / Low | Essential for third‑party claims; required for most client jobs |
| Workers' Compensation | Required / Admin | Protects employee medical/wage risk; mandatory with payroll |
| Preferred Vendor Agreements | Low / Low | Builds supply resilience; use for long‑lead and specialty items |
| Contingency Reserves | Low / Low | Shields small schedule shocks; size to project risk |
What Financial Controls and Insurance Types Are Essential for Contractors?
Baseline financial controls should include a standard estimating template, weekly job-cost reviews, a consistent invoicing cadence, and liquidity targets sized to payroll and receivables risk. Key insurance covers are General Liability (third‑party damage), Workers' Compensation (employee injuries), and Builders Risk (materials and work‑in‑progress). Each policy covers different exposure slices and should be sized to project scale. The short comparison below helps decide where premium dollars do the most good.
| Coverage Type | What It Protects | When to Use |
|---|---|---|
| General Liability | Third‑party injury and property damage | Use on all client‑facing jobs |
| Workers' Compensation | Employee medical and wage claims | Required when you have payroll |
| Builders Risk | Materials, equipment, and structure during construction | Use on larger or multi‑phase projects |
Start bidding with job-level tracking and verify insurance early — those actions prevent scope creep and limit disputes down the road.
Which Project Management and Supply Chain Strategies Reduce Operational Delays?
To reduce delays, systematize schedules, add buffers for critical-path items, keep a vetted vendor list, and track clear milestones so crews and materials arrive when needed. Simple KPIs — lead time variance, on-time delivery percentage, crew utilization — give operational visibility and early warning of problems. Use phased ordering for high‑lead items with deposit-triggered purchases to protect cash and avoid costly rush buys. Hold regular vendor reviews, set SLAs with repeat suppliers, and run short weekly plan-of-work meetings to keep crews and subs aligned. The next section covers legal and compliance risks that arise when contracts and regulatory duties aren’t clear.
Operational KPIs to monitor:
- Lead Time Variance: Track promised vs actual delivery times.
- On‑Time Delivery Rate: Measure percent of materials arriving on schedule.
- Crew Utilization: Compare productive hours to available hours.
What Legal and Compliance Risks Should Contractors Prepare For?
Legal and compliance risks show up as vague contracts, expired licenses, lien or bond exposure, and shifting regulations (for example, updated OSHA rules or procurement changes on public work). The problem is simple: gaps in contracts or missing licenses create openings during disputes or audits, and noncompliance can lead to fines or stop‑work orders that derail schedules. Prevent these by using standardized contract templates with clear scopes, payment and change‑order rules, scheduled compliance checks, and a dispute‑resolution pathway that aims to avoid litigation. The subsections that follow summarize contract best practices and regulatory trends to watch into 2025 and beyond.
How Do Clear Contracts and Dispute Resolution Protect Your Business?
Well‑written, scoped contracts remove ambiguity by spelling out deliverables, payment triggers, timelines, and the change‑order process — preventing most disputes before they start. Add explicit payment milestones and retainage language to protect cash flow, and include a tiered dispute resolution clause (negotiation → mediation → arbitration) to avoid expensive court fights. Tying payments to inspected, completed milestones turns subjective satisfaction into objective checkpoints that protect both sides. If a dispute happens, follow a documented flow: notice, corrective window, mediation, then arbitration — it preserves relationships and limits exposure. The next subsection highlights recent regulatory shifts to watch.
Must‑have contract elements:
- Scope of Work: Describe deliverables in measurable terms.
- Payment Schedule: Link payments to verifiable milestones.
- Change‑Order Process: Require signed change orders before additional work begins.
What Are the Latest Regulatory Changes Affecting Home Improvement Contractors?
Through 2025, regulators are tightening workplace safety enforcement, increasing focus on cybersecurity for contractors working with government or utilities, and updating licensing and procurement rules in several areas. These trends raise the compliance bar for contractors doing public work or handling customer data, making audits more likely and penalties costlier. Recommended actions: run periodic license checks, apply basic cybersecurity hygiene (strong passwords, access controls for project files), and schedule regular regulatory audits to catch gaps early. Staying on top of these items reduces the chance a regulatory issue delays permits or fails inspections. The next section explains how safety programs cut both claims and insurance costs.
To stay compliant, prioritize:
- License and Permit Review: Verify active licenses before contracting.
- Basic Cybersecurity Controls: Protect project and client data with access rules.
- Scheduled Compliance Audits: Run quarterly reviews of regulatory obligations.
How Can Safety and Workplace Hazard Prevention Reduce Contractor Risks?
Active safety programs lower incident rates, reduce claims, and protect your reputation by putting crews on consistent, documented protocols. The approach is straightforward: training, required PPE, daily site checks, and clear corrective actions turn hidden hazards into fixed conditions before they cause harm. A safety culture also pays: fewer lost‑time incidents, lower workers’ comp exposure, and—over time—reduced premiums. The next sections cover site safety best practices and how audits and emergency planning keep improvements in place.
Core safety program components to implement:
- Written Safety Plan: Site‑specific rules and assigned responsibilities.
- Onboarding Training: Safety orientation before the first field day.
- Daily Inspections: Short morning checklists to catch hazards early.
What Are the Best Practices for Site Safety Protocols and Employee Training?
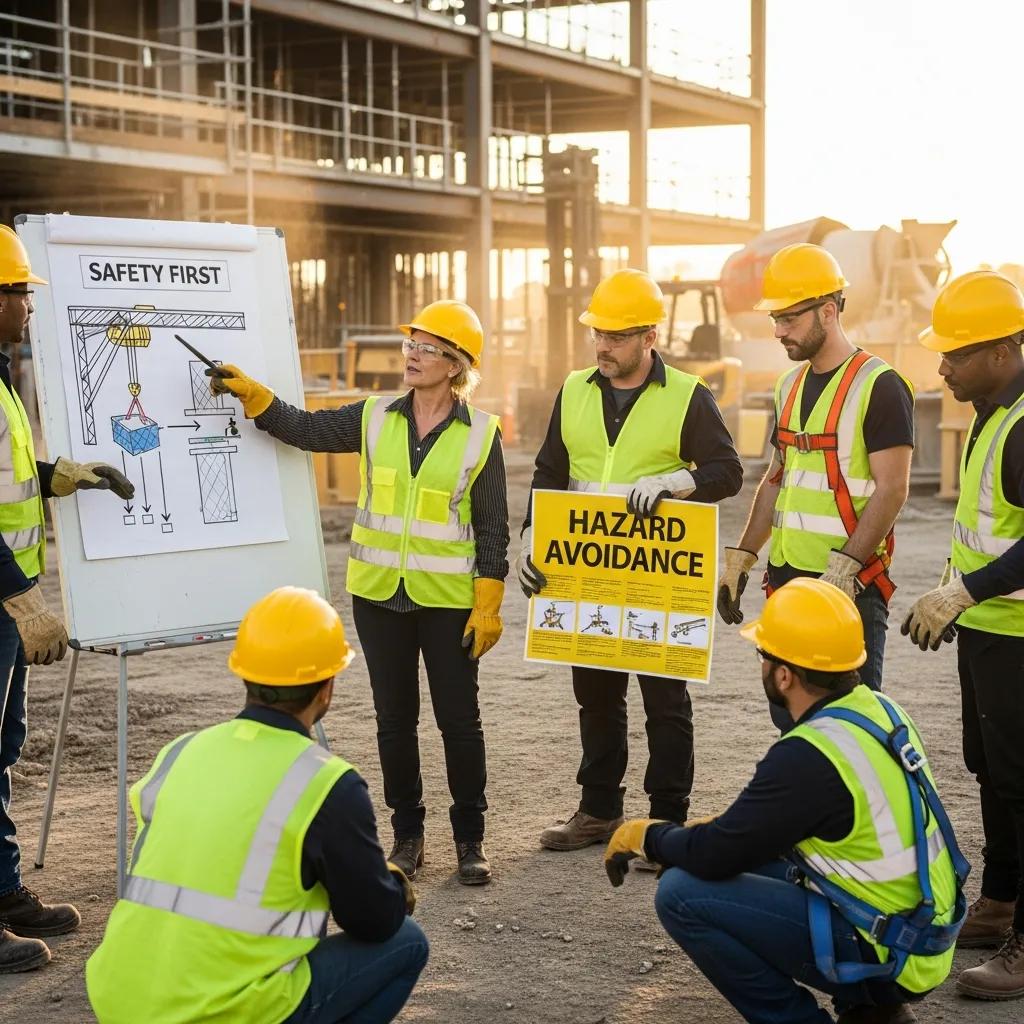
Start with a concise written safety program covering PPE rules, hazard communication, fall protection, and lockout procedures. Combine that with structured onboarding and recurring toolbox talks. Make training competency‑based — have workers demonstrate safe task performance — and keep attendance and corrective action records. Require daily inspections via a crew checklist and mandate hazard closeout within set timeframes so risky conditions don’t become normalized. Track leading indicators (inspections, toolbox talks) and lagging indicators (incidents, near misses) to close the loop and reduce incident rates. The following section explains emergency planning and audit steps that make these practices stick.
Daily safety inspection checklist:
- PPE Compliance: Confirm every crew member is wearing required PPE.
- Housekeeping: Remove trip hazards and secure loose materials.
- Equipment Condition: Verify machinery has current safety checks.
How Do Emergency Planning and Safety Audits Enhance Risk Management?
Emergency plans and audits turn reactive responses into repeatable procedures so incidents are contained, reported, and corrected quickly — reducing business interruption and claims. A strong emergency plan assigns roles, defines communication trees, sets reporting steps, and outlines recovery actions; regular drills reveal gaps and build crew confidence. Safety audits (scheduled and post‑incident) should follow checklists, feed corrective action plans, and assign owners to close findings. Track audits in a continuous‑improvement log that records issues, fixes, and trends so you can target training and resources where they cut risk most. The next section ties sales skills to financial resilience and shows how better selling reduces many risks below.
Audit cadence and follow‑through:
- Quarterly Audits: Full program compliance reviews.
- Post‑Incident Reviews: Immediate root‑cause analysis after events.
- Corrective Action Tracking: Document closure and confirm effectiveness.
How Does Sales Mastery Contribute to Reducing Business Risks for Contractors?
Strong sales skills make your business more resilient by stabilizing revenue, improving client selection, and clarifying scopes so projects run as planned. Consistent sales processes turn pipeline swings into predictable backlog, which makes cash flow steadier and staffing decisions easier. Sales behaviors that focus on rapport, professionalism, and clean closes reduce misunderstandings that lead to change orders or disputes — so sales work directly as risk mitigation. This program is designed to help home improvement sales professionals understand the course and training benefits, and to encourage sign‑ups for Tier 1 (free) or paid Tiers 2 & 3.
How Does Improving Close Rates Lower Financial Risk and Boost Profitability?
Raising close rates increases predictable revenue and cuts sales volatility, reducing the need for emergency credit and making payroll and purchasing steadier. Even a small conversion lift converts directly to higher monthly gross revenue. For example, a $100,000 monthly pipeline moving from a 20% to a 25% close rate nets an extra $5,000 each month without new leads — that eases working capital pressure. The RPC Framework — Rapport, Professionalism, Close — has helped contractors who collectively closed over $237M across 20+ trades. If you want to test the approach with no cost, Tier 1‑Foundation is available free to validate the methods on live leads.
Track these sales KPIs: close rate, average contract value, and days‑to‑signature — they directly tie into cash flow and staffing choices.
In What Ways Does Client Trust and Efficient Resource Allocation Mitigate Operational Risks?
When sales teams set clear scopes and build trust, projects start with aligned expectations, which cuts change orders and on‑site rework — common causes of schedule disruption and margin loss. Trust makes change negotiations faster and less adversarial, improving collections and reducing lien or litigation risk. Predictable sales outcomes let owners schedule crews and order materials without last‑minute rush premiums. Pairing stronger sales with planning shifts your operation from firefighting to predictable execution, lowering operational risk and improving utilization. The next section shows training options that tie sales skills to safety and operations.
To make this work in the field, prioritize:
- Scope Clarity: Put deliverables and exclusions in writing before starting.
- Expectation Setting: Tell clients expected milestones and timelines up front.
- Professional Follow‑through: Confirm decisions and changes in writing.
What Solutions Does Home Improvement Closer Offer for Risk-Aware Contractors?
Home Improvement Closer delivers tiered online sales training that reduces financial and operational risks by improving close rates, professional client interactions, and owner‑level systems for safe scaling. Start with free foundational concepts, then move to deeper coaching and ownership tools that include crew safety material. The table below summarizes each tier’s risk focus, core features, and pricing so you can choose what fits your current needs and growth plan.
| Tier | Primary Risk-Mitigation Benefit | Key Features & Price Point |
|---|---|---|
| Tier 1-Foundation | Immediate stability through foundational sales processes | Free entry-level training to validate sales methods with zero cost |
| Tier 2-Mastery | Consistent performance and fewer disputes | Ongoing coaching and systems to improve close rates; $149/month or $124/month annually |
| Tier 3-Ownership | Ownership-level systems and safety integration | Scaling playbooks, crew checklists, Safety Systems bonus; $250/month or $208/month annually; includes a 60-day money-back guarantee |
How Does the Tier 1-Foundation Course Support Basic Business Stability?
Tier 1‑Foundation teaches core sales habits that reduce near‑term financial risk by lifting close rates and clarifying scope at the point of sale — which cuts unpaid extras and surprise change orders. The course includes repeatable scripts, a Script Vault, and templates for proposals and payment conversations so crews start jobs with clearer client commitments and better funded materials buys. Because Tier 1 is free, you can test the concepts on live leads without financial risk and measure changes in close rate, average ticket, and days‑to‑signature before you upgrade. Onboarding is straightforward: enroll, complete the modules, apply scripts in the field, and track a few KPIs to validate impact.
Use Tier 1 as a low‑risk test channel to see measurable sales improvements before investing in paid coaching.
What Advanced Risk Mitigation Benefits Do Tier 2-Mastery and Tier 3-Ownership Provide?
Tier 2‑Mastery builds repeatable selling systems that reduce dispute frequency and smooth revenue by institutionalizing the RPC Framework with ongoing coaching; subscribe monthly or annually ($149/month or $124/month annually). Tier 3‑Ownership adds owner‑level controls and operational tools — an Exit Playbook, Crew Checklist, and a Safety Systems bonus — that address strategic and field safety risks while preparing the business to scale; pricing is $250/month or $208/month annually with a 60‑day money‑back guarantee. Together these tiers blend sales mastery with crew and safety systems so higher close rates come alongside better documentation and lower field risk. This program is designed to help home improvement sales professionals understand the course benefits and encourage sign‑ups for Tier 1 (free) or purchases of Tiers 2 & 3.
Transparent tiered pricing and the money‑back guarantee make progression low risk while improving both sales and operational systems.
This article covered the main risks contractors face and offered layered, practical mitigations — from immediate financial controls and insurance choices to operational KPIs, safety programs, and sales mastery — so you can lower exposure and build a more resilient contracting business.
Frequently Asked Questions
What steps can contractors take to improve cash flow management?
Improve cash flow by enforcing clear payment terms — deposits, milestone billing, and prompt invoicing. Track job costs against estimates weekly so you spot overruns early. Keep a reserve for surprises and run credit checks on new clients. Job costing software gives visibility into profitability and helps you make smarter purchasing and staffing decisions.
How can contractors ensure compliance with evolving regulations?
Stay compliant by running regular audits and keeping licenses current. Maintain a compliance calendar for renewals and regulatory deadlines. Train staff on protocol updates and use standardized contract procedures. When needed, consult industry groups or legal advisors to anticipate changes and adjust practices before audits happen.
What role does employee training play in risk management?
Training is a cornerstone of risk management. Regular safety instruction, onboarding, and refreshers teach crews to spot and correct hazards. Training should cover PPE use, emergency response, and hazard recognition, and include documented competency checks. Well‑trained crews mean fewer incidents, lower claims, and better overall project outcomes.
How can contractors effectively manage subcontractor risks?
Manage subcontractor risk with clear agreements that state expectations, deliverables, and payment terms. Vet subs thoroughly — check references and past work — and keep regular performance conversations. Maintain a diverse, pre‑qualified subcontractor pool so you’re not dependent on a single provider if problems arise.
What are the benefits of implementing a safety culture in a contracting business?
A safety culture reduces accidents, lowers insurance costs, and boosts crew morale. It encourages proactive hazard reporting and corrective action, protecting people and reputation. Clients notice too — strong safety practices can make your business a preferred contractor and improve project outcomes and profitability.
How can technology assist in risk management for contractors?
Technology helps by automating job costing, scheduling, and safety reporting. Project management software tracks timelines and subcontractor performance. Mobile apps let crews report issues in real time. The right tools increase visibility, reduce errors, and let you act on problems before they grow.
Conclusion
Effective risk management protects your business and helps projects finish on time and on budget. By addressing financial, operational, legal, and safety risks with practical controls, you’ll strengthen cash flow, reduce disputes, and improve crew safety. Explore our tiered training programs to tighten your sales process and operational systems — start with the free Tier 1 course to see results before you invest in deeper coaching.